The local real estate market has changed as 2026 begins. After sharp price rises from 2020 to 2023, conditions now appear more moderate and stable. Many buyers question whether a Singapore property remains a viable portfolio asset amid current financing costs and regulatory shifts.
Success now depends on your goals, holding period, and risk tolerance. Limited supply still supports demand and long-term value for careful buyers. Every modern investor must understand financing capacity and location.
This guide offers a practical way to navigate these challenges. We will assess possible returns, tax effects, and emerging technology’s impact on your next Singapore property investment. These factors can show whether today’s market matches your financial goals.
Overview of Singapore’s Real Estate Market in 2026
Investors studying property market singapore now see steady, measured growth. Rapid price gains have cooled, but the sector remains strong. This shift supports a more sustainable path for long-term capital growth.
Data from 2025 shows this strength: new private home sales reached 10,815 units. This rise reflects renewed buyer confidence after developers released more projects. The sales volume suggests strong demand despite wider economic changes.
Recent comparisons show the cooling trend clearly. Prices rose 6.8% in 2023 and 3.9% in 2024. By contrast, 2026 shows slower but steady positive growth.
Lower mortgage rates and strong occupier demand support this stability. These factors create a firm base for investors interested in real estate in singapore. Still, investors must choose assets with greater care.
Moderate price growth still creates opportunities, but it changes the strategy. Investors should focus on entry price, rental demand, and careful leverage. Success in property market singapore now requires planning and a long-term investment view.
Government Policies Affecting Property Investment
Singapore’s property rules strongly shape local real estate trends. They aim to keep the market stable and limit excessive speculation, which affects singapore property prices. Investors must track these rules to estimate potential returns accurately.
The biggest change for international buyers is the 60% Additional Buyer’s Stamp Duty (ABSD) rate. This large tax changes the cost of residential purchases for non-Singaporeans. It discourages speculation and pushes investors toward long-term income instead of quick gains.
Short-term flipping became riskier after the July 2025 expansion of the Seller’s Stamp Duty. The policy adds heavy taxes to properties sold during a short holding period, affecting singapore property prices for quick exits. Investors face more tax exposure without a long-term holding strategy.
Borrowing capacity is further limited by changes to the Total Debt Servicing Ratio (TDSR) and mandatory stress testing. These rules help prevent buyers from borrowing too much during changing interest rates. Also, lowering the HDB loan-to-value limit from 80% to 75% requires a larger upfront cash payment.
Together, these rules create a disciplined market for all participants. These hurdles may seem hard, but they protect the market’s long-term health. Anyone navigating singapore property prices must understand these limits in the current climate.
Types of Properties in Singapore
Choosing the right asset class is vital when seeking a Singapore property for sale. The market has several categories, each offering different benefits in tenure, maintenance, and possible returns.
Public housing, known as HDB flats, remains popular with many residents. Private condominiums offer lifestyle facilities such as pools and gyms. Landed homes offer more space and privacy, but usually cost more and require greater upkeep.
Executive Condominiums (ECs) combine features of public and private housing. They later become private properties, making them popular for long-term capital appreciation.
Commercial and industrial assets may offer yield profiles that differ from residential units. Investors seeking a hands-off option can use Real Estate Investment Trusts (REITs). They provide market exposure without direct property management.
Learn the framework of the Core Central Region (CCR), Rest of Central Region (RCR), and Outside Central Region (OCR). These zones help investors match budgets with local demand patterns.
High-net-worth buyers often choose the CCR for its prestige and prime location. By contrast, OCR has drawn strong recent interest. Data show that OCR housing led price growth in the first quarter of 2026.
Liquidity and target tenant profiles differ greatly across these segments. For a high-yield commercial space or stable residential Singapore property for sale, align each choice with your goals to succeed.
Popular Districts for Property Investment
Singapore’s varied property market requires a clear plan for choosing a location. Instead of chasing guaranteed winners, investors should match districts with their financial goals. A thorough singapore property market analysis shows that success often depends on choosing the right market segment.
The Core Central Region (CCR) often suits investors seeking prestige and high liquidity. These properties often command premium values because they sit near the financial hub and luxury amenities. Although entry costs are higher, long-term investors may gain potential capital appreciation.
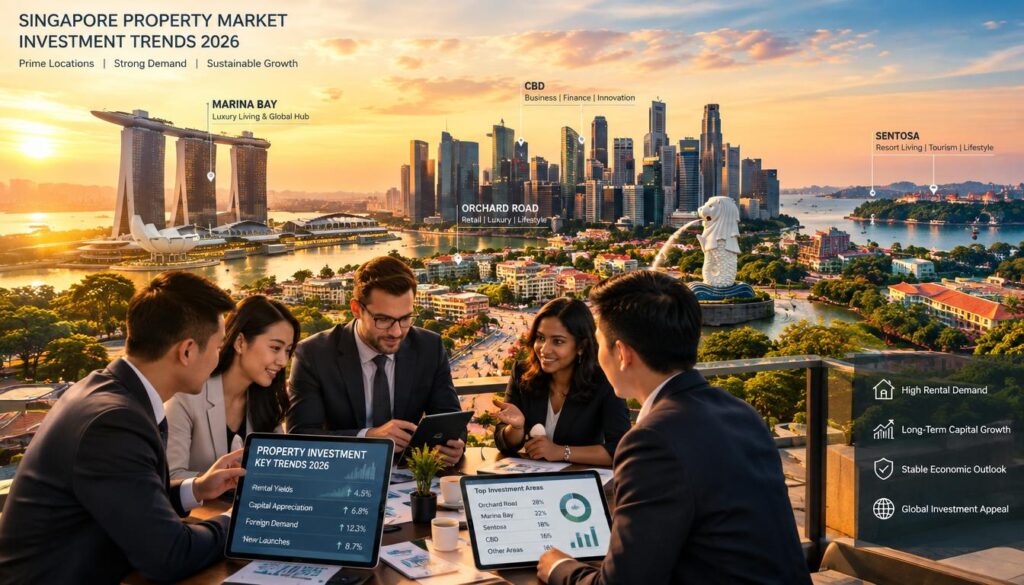
For those seeking lifestyle and value, the Rest of Central Region (RCR) offers a compelling middle ground. These areas often have strong transport links and lie near major employment nodes. Many investors find stable rental yields here, which matter when assessing current singapore property prices.
Families and investors seeking affordability often favor the Outside Central Region (OCR). These districts often draw local residents because they sit near schools and neighborhood amenities. When assessing them, look for upcoming government redevelopment plans that could drive future growth.
Before deciding, conduct a deep review of recent comparable transactions. Do not rely only on historical returns; current asking prices may already reflect them. Instead, assess specific micro-location factors, such as upcoming transport links and local infrastructure improvements.
A disciplined approach to location analysis is better than blindly following market trends. By weighing trade-offs among the CCR, RCR, and OCR, you can make an informed choice. Keep your investment strategy grounded in data-driven insights about singapore property prices and broader market trends.
Investment Strategies for 2026
If you are exploring the market for Singapore property for sale, modern investment strategies are essential for success. The current market favors medium- to long-term holding over speculative short-term gains. With the expanded four-year Seller’s Stamp Duty framework, traditional “flipping” is less attractive and financially riskier for most investors.
Instead, savvy investors favor buy-and-hold strategies that create steady rental income. Value-add opportunities may also work, because smart renovations can improve an asset’s appeal and rental potential. To diversify without direct ownership, consider REITs, property-focused stocks, and property ETFs as liquid alternatives to physical real estate.
When evaluating a purchase, look beyond advertised gross returns. Calculate the true net rental yield using vacancy assumptions, maintenance costs, property taxes, and financing expenses. Base realistic capital appreciation on market data, not optimistic projections.
To make a sound decision when seeking Singapore property for sale, follow a structured checklist. First, compare the entry price with recent transaction data from the area. Consider how future infrastructure, such as new MRT lines or commercial hubs, could affect value over time.
Assess local tenant demand to help keep your investment occupied. Check the remaining lease tenure, which strongly affects long-term value and financing options. Finally, evaluate the asset’s exit liquidity, so you can sell efficiently when realizing gains.
These key measures can help you navigate the market for Singapore property for sale with confidence. Disciplined financial planning and asset selection remain the most reliable path to building wealth in the current economic climate.
Financing Your Property Investment
Smart investors know successful singapore property purchases begin with strong financial planning. Beyond the purchase price, plan for cash savings and Central Provident Fund (CPF) balances. Balancing these assets keeps you liquid while building long-term equity.
When choosing a bank loan, you will compare fixed-rate packages with SORA-linked loans. Fixed rates protect against market changes, while SORA-linked loans may cost less initially during favorable economic cycles. All banks use a 4% stress-test floor to assess affordability and prepare for possible rate hikes.
Calculating the true capital needed for a singapore property goes beyond the down payment. Include the Buyer’s Stamp Duty (BSD), legal fees, and potential Additional Buyer’s Stamp Duty (ABSD), if applicable. Also reserve money for renovation, ongoing maintenance, and property taxes to build a realistic budget.
Prudent financial management means keeping at least six months of expenses in an emergency reserve. This buffer protects you from unexpected income disruption or long vacancy periods. Stress-test repayments against higher interest rates to keep your investment sustainable during market downturns.
Your financing structure shapes the health of your singapore property portfolio. Carefully assess your loan tenure and interest-rate exposure to reduce unnecessary risks. Discipline with these obligations protects your capital and improves long-term returns in the competitive real estate market.
Risks Associated with Singapore Property Investment
Singapore property investment requires careful attention to hidden risks. Investors must watch interest rate changes, vacancy periods, and new rules, even when real estate seems stable. High debt can become unaffordable when market conditions change.
Many newcomers expect high gross yields after seeing advertisements for 4% returns. Yet taxes, maintenance fees, agent commissions, and stamp duties can reduce 4% to a net return of 1.5% to 2.5%.
A major Singapore property investment risk is becoming asset-rich but cash-poor. If much of your net worth sits in one residential unit, you may lack cash during employment interruption or retirement. This concentration risk grows if you cannot sell quickly or rental demand drops significantly.
Lease decay can reduce the value of older properties over time. As the remaining leasehold tenure shortens, financing choices become limited, reducing your pool of future buyers. Unexpected maintenance costs may also arise in older developments, reducing projected profits.
Protect your capital with a strict risk-control checklist. Keep borrowing at conservative levels and maintain a cash buffer for mortgage payments during vacancies. Diversify beyond real estate so one market sector does not control your portfolio.
Conduct thorough tenant screening and maintain comprehensive insurance coverage. A clear exit plan is essential for every successful investor. Recognizing risks early supports informed decisions and protects your financial future from market volatility.
The Role of Technology in Real Estate
Technology is reshaping how investors approach real estate in Singapore. Modern platforms provide instant access to comprehensive transaction databases. They let users compare current asking prices with historical sales data.
This transparency helps investors identify fair market value before committing to a purchase.
Digital tools have changed property viewings through high-definition virtual tours. These tours let buyers inspect homes worldwide and save time during early screening. Affordability calculators and electronic documents also make financing easier.
Data-led neighborhood analysis helps investors study real estate in Singapore. Investors can model rental yields by entering costs, including maintenance fees and property taxes, into sophisticated software. These insights support careful portfolio management and long-term growth.
For investors who want market exposure without ownership, REIT platforms and robo-advisors offer liquid options. These services provide lower-cost entry to commercial and residential assets. They help investors diversify holdings across economic sectors.
Technology supports investors but does not replace human expertise. Investors must still inspect properties in person to check their actual condition. Professional due diligence, thorough title checks, and independent financial advice remain essential for real estate in Singapore.
Relying solely on digital data can hide details that only experienced professionals can spot.
The Impact of Foreign Investments
Understanding international investors is essential for anyone tracking the latest singapore property news. Singapore remains a premier global destination for capital because of political stability and a robust regulatory framework. These strengths make it a safe haven for wealth preservation.
The residential sector changed after Singapore introduced a 60% Additional Buyer’s Stamp Duty (ABSD) for foreigners. This high tax cooled speculative residential purchases. Many international buyers now choose more selective, long-term strategies when entering the market.
Institutional investors and sovereign wealth funds remain vital to Singapore’s commercial landscape. Unlike individual residential buyers, they often target high-value office spaces, logistics hubs, and retail assets. Their activity adds liquidity and supports development across the city-state.
REIT participants deepen the market by pooling capital for large-scale property acquisitions. This institutional support keeps prime-market demand strong when residential transaction volumes fluctuate. Following singapore property news helps investors distinguish between these market segments.
Foreign capital has many effects and continues to change with government policies. Overseas residential demand has softened, but institutional interest remains a pillar of the local economy. Investors should monitor singapore property news to understand how global capital flows shape future pricing expectations.
The Future of Singapore Property Investment
Looking ahead, singapore property market analysis points to stability and selective growth. Our base case expects moderate price growth, supported by limited new housing supply and steady demand from local households. This balance supports long-term capital preservation.
Investors must still watch risks that could disrupt this path. Global economic volatility, employment changes, and renewed inflation remain important variables. The government may add cooling measures if the market overheats, directly affecting the property market singapore landscape.
Aging assets and redevelopment projects offer opportunities for investors with the right expertise. These properties need major capital and technical knowledge, but they can deliver high returns. Investors should weigh renovation costs against long-term value growth in established districts.
These factors make a fixed investment approach outdated. Past performance or one forecast can cause missed opportunities or unexpected losses. Instead, use a dynamic singapore property market analysis that responds to economic data and policy shifts.
The future of the property market singapore depends on how investors manage these changing conditions. By staying informed and updating your strategy, you can help your portfolio withstand market changes. Success requires continuous learning and a disciplined, data-driven mindset.
Expert Opinions on the Real Estate Market
Recent singapore property news shows investors view long-term capital appreciation differently. Analysts say property has brought steady returns, but investors must read these figures carefully. Investors compare property’s roughly 4% annualized return with equity markets, but this comparison can mislead.
The main difference is leverage. Most homeowners finance much of their property purchase, which boosts returns on their own cash. With borrowed capital included, the equity yield often looks better than unleveraged stock market returns.
However, experts warn that leverage cuts both ways. It can boost gains, but it also raises losses when market conditions worsen. Real estate is less liquid than stocks, so owners cannot quickly turn assets into cash during financial emergencies.
Current singapore property news also points to hidden ownership costs. Investors must include transaction costs, stamp duties, and ongoing maintenance, which reduce net profits. These costs often surprise new investors who focus on gross rental yields instead of the asset’s total holding cost.
Diversification remains central in professional commentary. Depending too much on one property creates dangerous concentration risk in a portfolio. Experts say property is a stable asset, but it should support other investments, not be your only path to wealth.
Finally, historical performance does not guarantee future appreciation. As noted in recent singapore property news, regulatory changes and global economic shifts can quickly change the market. A prudent investor balances growth potential with market risks and personal financial goals.
Conclusion: Evaluating the Viability of Investment
Success in today’s market requires active calculation, not passive optimism. A singapore property can remain a viable asset for buyers with enough capital and manageable debt. A long holding period helps investors weather market cycles.
Market data shows prices rose 3.4% in 2025 and 0.9% during the first quarter of 2026. These figures point to slower growth than in previous years, while substantial taxes make automatic gains unlikely. Evaluate total returns after financing, property tax, maintenance, vacancy, stamp duties, and selling costs.
Use a practical decision framework: define your specific investment objective, then compare locations and property types for your budget. Stress-test financing for interest rate shifts, preserve liquidity, and diversify beyond a single singapore property investment. Proceed only when conservative assumptions keep the numbers viable and protect your long-term financial health.